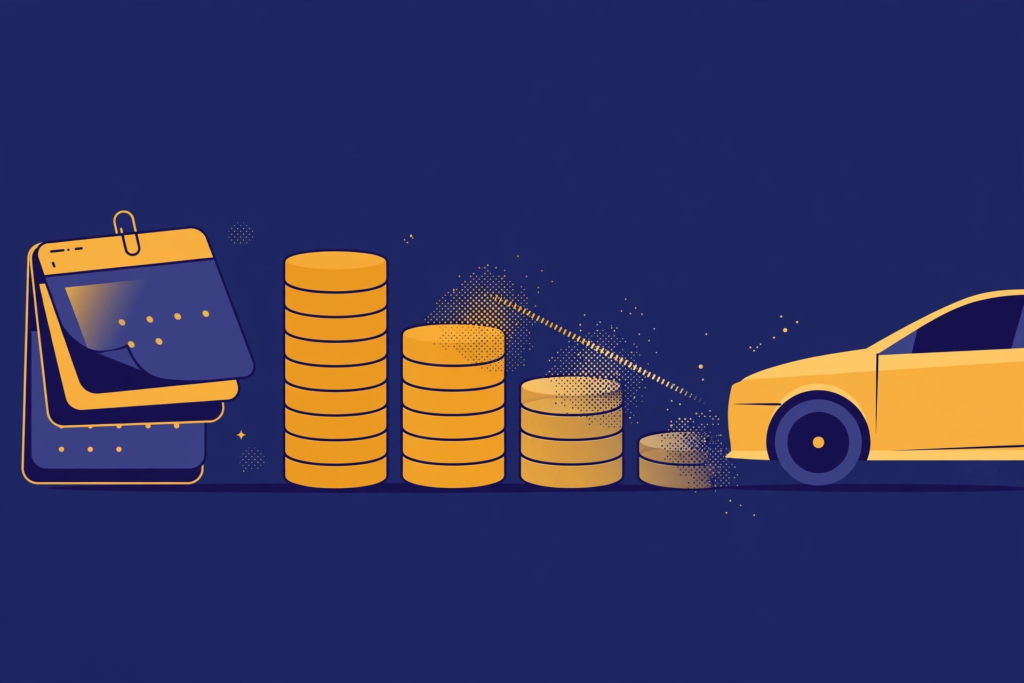
A vanishing deductible — sometimes called a diminishing or disappearing deductible — rewards you for claim-free driving by shrinking your deductible a little each year until it can reach zero. File a claim on a $500 deductible after several clean years, and you might pay nothing out of pocket. It’s an appealing concept, but vanishing deductible programs come with rules, costs, and trade-offs worth understanding before you sign up.
Here’s exactly how they work, what they cost, and whether the math favors you.
Vanishing deductible at a Glance
Vanishing deductible explained: how it reduces your deductible yearly, what it costs, pros and cons, and whether to add it in 2026. Below, we break down vanishing deductible in detail so you can act with confidence.
Table of Contents
How Vanishing Deductibles Work
The basic mechanism
You start with your normal deductible — say $500 for collision and comprehensive. For each consecutive claim-free year (some programs use policy terms rather than calendar years), the insurer reduces your deductible by a fixed amount, commonly $50 or $100 per year. After enough clean years, the deductible can vanish entirely to $0.
A simple example
- Year 1: $500 deductible
- Year 2 (claim-free): $400 deductible
- Year 3 (claim-free): $300 deductible
- Year 4 (claim-free): $200 deductible
- Year 5 (claim-free): $100 deductible
- Year 6 (claim-free): $0 deductible
Exact schedules vary by insurer — some reduce faster, some cap the minimum above zero, and some apply it to collision and comprehensive separately.
What resets it
File a claim, and the deductible typically resets to its original amount (or partially resets, depending on the program). The clock then starts over. This is the core trade-off: the benefit rewards you for not claiming, and claiming wipes out the progress.
Earned vs. Purchased Programs
Included free
Some insurers build vanishing deductibles into their standard offering as a loyalty feature — no extra charge, applied automatically to qualifying policies.
Paid add-on
Others sell it as an endorsement costing extra per term. When it’s a paid add-on, you need to weigh the cost against the benefit realistically.
Enrollment requirements
Common conditions include:
- Available only on collision and comprehensive deductibles (not liability — liability has no deductible)
- May require minimum starting deductibles (e.g., $250 or higher)
- All drivers on the policy typically must remain claim-free for the reduction to continue
- New customers may need to wait a term before reductions begin
The Math: Is It Worth Paying For?
When the numbers work
Consider a paid vanishing deductible add-on costing a small amount per term, reducing your $500 deductible by $100 per claim-free year:
- If you go five claim-free years, you’ve effectively banked $500 in deductible reduction
- One claim in year six costs you $0 out of pocket instead of $500
- The total add-on cost over those years is typically far less than the deductible saved
For drivers who rarely claim — which is most drivers — the expected value is positive.
When to think twice
- You claim frequently. If you file collision or comprehensive claims every couple of years, you’ll keep resetting and never reach the low deductibles.
- Your deductible is already low. Vanishing from $250 to $0 saves less than vanishing from $1,000.
- The add-on is expensive. Compare its cost against simply lowering your deductible directly — sometimes buying a lower deductible outright is cheaper than the vanishing feature.
The behavioral angle
There’s a subtle incentive worth noting: vanishing deductibles discourage small claims (since claiming resets your progress), which is generally good — small claims often cost more in future premium increases than they’re worth. The program aligns your incentives with smart claiming behavior.
Vanishing Deductible vs. Related Features
Accident forgiveness
Accident forgiveness protects your rate after an at-fault accident; vanishing deductible reduces your out-of-pocket cost when you claim. They address different pains and pair well together — but note that using one may affect the other (a forgiven accident may still reset your vanishing deductible).
Simply choosing a lower deductible
A $250 deductible costs more in premium than a $500 deductible, every term, forever. A vanishing deductible gives you the premium savings of the higher deductible plus the claim-time benefit of the lower one — if you stay claim-free long enough.
Disappearing deductible vs. deductible waiver
Some policies waive deductibles in specific situations (e.g., glass repair, or accidents with uninsured drivers where you’re not at fault). Those are separate features — vanishing deductible is the gradual-reduction program.
Maximizing the Benefit
1. Enroll early. Reductions accrue over time, so starting the clock sooner is always better.
2. Keep all drivers clean. One driver’s claim can reset the whole policy’s progress — it’s a household effort.
3. Handle tiny damage out of pocket. Paying for a minor scratch yourself preserves both your vanishing progress and your claims-free record.
4. Track your current deductible. Check your declarations page or app — many drivers forget their deductible has shrunk until claim time (a pleasant surprise, but better planned).
5. Re-evaluate if you switch insurers. Vanishing progress doesn’t transfer; factor the lost progress into switching decisions.
Frequently Asked Questions
How fast does a vanishing deductible disappear?
It depends on the insurer’s schedule — commonly $50 to $100 off per claim-free year. Reaching zero from a $500 deductible typically takes several years of clean driving.
Does filing any claim reset my vanishing deductible?
Usually a collision or comprehensive claim resets it, since those are the coverages it applies to. Liability-only claims generally don’t affect it. Check whether your program does a full or partial reset.
Is vanishing deductible free?
Sometimes — many insurers include it as a loyalty feature at no charge. Others sell it as a paid endorsement. Ask your insurer which version you have or are being offered.
Does it apply to all my vehicles?
Typically yes, per policy — the reduction applies to the collision and comprehensive deductibles on covered vehicles. Confirm whether it’s per-vehicle or per-policy in your program.
What happens to my vanishing deductible if I switch insurance companies?
You lose the accumulated reduction — it doesn’t transfer. This is a real switching cost to weigh when comparing quotes, especially if you’re close to zero.
A vanishing deductible is a patient driver’s reward: stay claim-free, and your out-of-pocket cost on future claims melts away. It’s most valuable for careful drivers who rarely claim and carry moderate-to-high deductibles. If yours is free, enjoy it; if it’s a paid add-on, run the simple math against your claim history. Either way, pair it with smart claiming habits — and compare quotes to make sure the insurer rewarding your clean record is also giving you the best base rate.
For official guidance on vanishing deductible, see the Insurance Information Institute’s coverage guide. And if this breakdown helped, the related guides below go deeper on vanishing deductible saving strategies you can use right away.